Showing posts with label PBOC. Show all posts

Monday, November 16, 2015

Australia reports strong jobs numbers!


After finishing in second place last week the AUD was able to supplant the USD, as it failed to maintain its lead in the week after the exceptionally strong U.S. jobs report which had helped fan expectations of a December Fed rate hike. Similar to last week, it was the jobs report that helped power up the performance of the domestic currency. Australia recorded the largest payroll increase since early 2012 as the economy added 59K jobs in October, beating expectations of 15K and a -1K decline in September. The unemployment rate dropped to 5.9% from 6.2% a month ago, marking the lowest level since May 2014, while the participation rate picked up to 65% from 64.9% in the prior month. The internals were also stellar as both full-time and part-time jobs rose last month with the former gaining 40K (following September upwardly revised 10K decline) and the latter adding 19K (compared with September's 10K increase). Just to put these numbers into perspective, the 59K October jobs gain would equate to over 800K new jobs in the U.S.; and just last week the market was cheering about the 271K increase.

Surprisingly, the GBP was able to match the AUD’s gain after last week’s disastrous Super Thursday performance which was outlined in detail in last week’s Dispatch. The labor market also played a role in relation to the domestic currency 1.21% gain as the unemployment rate fell unexpectedly to a fresh seven-year low of 5.3%. Meanwhile, employment rose by 177,000 over the quarter, meaning there are now 31.2m people in work, according to the Office for National Statistics. Comments made by Bank of England Governor Mark Carney encouraged speculation that the central bank could move on interest rates sooner than previously suggested. Carney told Bloomberg he believes the U.K. economy, which is forecast to grow at 2.7% this year, may soon have the right conditions for a rate rise.

The odd person out last week belonged to the CAD with a weekly decline of 0.15%. The main culprit was the 8% drop in the price of crude as prices fell toward the $40 handle. The decline this week came from fresh signs of increasing supply due to abundant supplies and slackening demand, especially in China. The IEA said global oil-demand growth will slow to 1.2 million barrels a day in 2016, after surging to 1.8 million barrels a day this year, a five-year high. Having said this, Friday’s tragic terrorist attack on Paris could further slow the global economy and demand for oil. Thus, weakening oil prices may exert even more downside pressure on the CAD to start the week on top of key reports due this week on inflation and retail sales.

Last Thursday, no less than six Federal Reserve policy members spoke. We won’t bore you with the details of each speech – the common take away was that the Fed is ready to raise interest rate if the data supports the move.

IMF Will Decide the Near-Term Future of the Yuan

Most market analysts have little doubt the that Chinese yuan will one day be part of the International Monetary Fund’s special drawing rights (SDR) at some point in the future, but very few believe that it will happen by the end of this month. On November 30th the IMF Managing Director Christin Lagarde will make a decision about the CNY becoming part of the SDR, which is a multilateral institution basket of currencies that include the USD, EUR, GBP and JPY. However, if the IMF surprises us all, the inclusion of the CNY into the SDR could be the spark that fires the yuan rocket in the years ahead as a global reserve currency, likely replacing the Japanese yen and Great Britain pound in the currency hungry emerging market central banks.
It was only a few months ago that several media outlet reports suggested that people inside the IMF were saying that the yuan was not yet equipped for prime time. However, more recently Ms. Lagarde stated, “The IMF staff assessed that the RMB [CNY] meets the requirements to be a ‘freely usable’ currency and…proposes that the Executive Board determine the RMB to be included in the SDR basket as a fifth currency, along with the British pound, euro, Japanese yen, and the U.S. dollar.” She added that the staff also found that Chinese authorities have addressed “all remaining operational issues identified in an initial staff analysis submitted to the Executive Board in July. I support the staff’s findings.” This is big news.

The decision to include the CNY into the SDR will not rest entirely on Ms. Lagarde. The market at large will have a say as well. Meanwhile, China is busy building up its local bond market with the hope that it will be seen by Asian institutional investors, emerging market central banks and big sovereign wealth funds as a safe haven alternative to U.S. Treasury bonds at some point in the near future.

In August, the Peoples Bank of China (PBoC) allowed the CNY to trade within a wider band, which resulted in a weaker yuan. The result was furious push-back from Western economies because they felt that it was a protectionist measure to manipulate its currency in order to save its export
manufacturers at a time when the economy is growing slower than it has in years. However, it’s important to keep in mind that the yuan at the time was the strongest in the region – stronger than the likes of South Korea, Taiwan and the Singapore Dollar. Moreover, the trading band actually gave the market more say to sell the CNY short and weaken it against the USD and EUR. In its history, this is the closest China has come to free-float the CNY. China still has a long road ahead, but its goal to become a reserve currency has gain momentum. However, the PBoC’s strict control on the flow of the yuan will continue to impede its progress and restrict it from becoming a basket currency, as all other currencies in the IMF’s SDR are determined by the market.

Tuesday, October 27, 2015

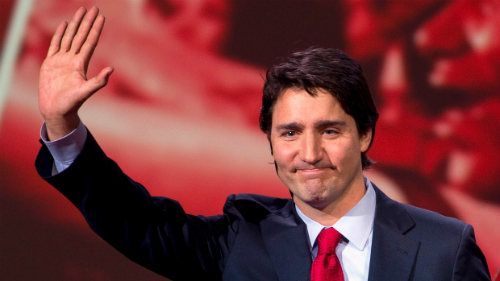
Welcome Prime Minister Trudeau! Canadian voters have decided he is ready to run this country!


Last week Canadians voted in a new federal government, led by Justin Trudeau, the son of former Prime Minister Pierre Elliot Trudeau. The fact that the CAD was down almost 2% on the week has more to do with the low inflation readings and soft oil prices than the rise in power of the traditional centrist Liberals. Canadians were able to cut through the negative ads by the ruling Conservatives portraying Trudeau as a good looking guy with “nice hair” that simply wasn’t ready to run a country. Trudeau made a point of pledging to run modest budget deficits for three years to kick-start the economy through investment in public transport, building affordable housing, and other infrastructure projects. Trudeau’s win may be a sign that the anti-austerity regime in Western governments is about to turn, especially since it’s becoming more and more obvious that central bank stimulus is running out of gas. All eyes will be on him and his government because if he can pull this off, it will be a road map for other governments to follow.

The US dollar index was on the cusp of breaking down from its recent ranges. However, it was not to be as a combination of rate cuts by the central bank of China and dovish jawboning by ECB President Mario Draghi help the USD bounce off support and surge higher to outperform the rest of the major currencies. The People’s Bank of China on Friday cut interest rates for a sixth time in a year after data last week showed that GDP grew 6.9% in the third quarter from a year earlier, the slowest pace in more than six years. China's central bank cut the benchmark rate by 25 bps on a one-year loan to 4.35%. The PBOC also increased the amount of money available for lending by reducing the level of reserves banks are required to hold. This was the latest signal of a major central bank's commitment to unusually low rates to try to spur economic growth.
Meanwhile on Thursday, ECB President Draghi sent his own strong signal that the bank is prepared to expand its stimulus program, which sent the euro down 2.96% on the week. Draghi outlined the options available: extend the end-date for QE purchases beyond the end of September 2016, increase the size of the QE program, broaden the types of bonds purchased, and/or lower the deposit beyond its current level of minus 0.2%. Like all global central banks, the ECB is worried about too-low inflation – inflation rates are barely above zero and far below the 2% rate that most consider optimal. Expectations are now set for more easing at its December policy meeting.

What War Hath Wrought

Currency wars are a zero-sum game. Who is eating whose lunch is an interesting question, but a more important query is whether the pie itself is growing. The ‘pie’ in this instance is essentially global GDP. Everyone would agree that the global economy moving forward is considerably diminished because the rate of global trade and integration is shrinking, which has been a key driver over the past 60 or so years. Growth has indeed slowed, but the only bump in the road we see in our rear-view mirror was the financial crisis of 2008/09. So, who is winning the currency war post-2009? Like we said above, currency wars are a zero-sum game, so nobody is winning. However, there has been a huge change in the currency landscape because earlier this month China’s yuan overtook Japan’s yen to become the fourth most used currency for global payments, brushing off a surprise devaluation in CNY to rise to its uppermost ranking ever and advancing its assertion for reserve status.

According to a report published in early October, the Society of World Interbank Financial Telecommunications (SWIFT), the proportion of international transactions denominated in yuan climbed to a record 2.79% in August compared to 2.34% in July. The icing on the cake for the CNY would be inclusion into the IMF’s twice-a-decade review of its Special Drawing Rights (SDR) basket, which is currently comprised of the USD, EUR, JPY and GBP. If the yuan does get included into the basket, it could mean as much as $1 trillion of inflows into the currency. Inclusion into the SDR would also likely promote more reform in China, and it is widely known that the People’s Bank of China Governor Zhou Xiaochuan is keen to liberalize the markets. Fingers crossed!

The only obstruction left to overcome to even loftier heights for the CNY is removing the barriers of foreign access to mainland China’s markets. According to Economists Tom Orlik and Fielding Chen of Bloomberg Intelligence:

The People’s Bank of China continues to come up with ingenious workarounds to promote yuan internationalization without capital-account opening. Rapid growth of the dim sum bond market means international investors don’t need to bring funds into China to buy yuan assets. Offshore yuan bond issuance rocketed to $270 billion in 2014, up 153 percent from $107 billion in 2013.

Swap agreements totaling 3.5 trillion yuan have now been signed between the PBOC and more than 30 other central banks. Currency swaps can be used by trade partners to cushion against a balance of payment crisis. As such, they reduce other central banks’ need for dollars and mean the yuan is already playing a role as a de facto reserve currency.

The start of Mutual Market Access between Shanghai and Hong Kong equity markets last year represented a step toward market opening. So far, its reception has been lukewarm, with more than 50 percent of the inbound quota and 70 percent of the outbound still unused.

The yuan’s astonishing progress into global markets validates President Xi Jinping’s determination to
test the supremacy of the dollar and a global economic order, which has been long dominated by Europe and the United States. China’s greatest incentive to pick up the pace of reform is to remove the hegemony of Western economies. The U.S. is very confident that it will never be dethroned has reprimanded China on and off for decades for keeping the yuan weak to boost exports, says it hasn’t done enough to dismantle controls. A more widely used currency would raise China’s influence in setting prices of commodities from oil to orange juice and give individuals and companies on the mainland more choice with what to do with their savings – not to mention her influence in global geopolitics. As the CNY makes its lengthy march to convertibility, China becomes susceptible to swings in the currency and money flows that could exacerbate its economic slowdown.